Short answer
If you are wondering how to teach kids to save money, start with one goal. It should be a specific thing your child picked, exciting enough to matter and cheap enough to finish. Size it to their age: a few weeks of saving at 8–10, several months for teens. Then split the price into equal steps and let your child watch them fill.
Birthday money arrives on Saturday and is gone by Monday. The three labeled jars from last spring now hold a hair tie and a trading card. You have explained that saving is good. Your child agrees, pleasantly, and buys the slime.
None of this means your child is bad with money. "Save for later" is just too vague to act on. What works better is narrower: one goal, sized to finish, with progress they can see.
Start with one goal worth saving for
Saving is a habit, but kids learn it through a goal. The U.S. Consumer Financial Protection Bureau lists "planning, saving, and sticking to goals and priorities" as a core milestone for ages 6 to 12. It pairs that with starting "a habit of putting money aside for things you want" (CFPB, Money as You Grow). Things you want. Not "the future."
What the research says
The skills under saving start early. A CFPB report names executive function as one of three building blocks of adult financial capability. It covers the mental processes used to plan, focus, remember and juggle tasks. In its model, money habits are readily picked up at 6 to 12. Independent money decisions grow from 13 on (CFPB, 2016). It is an official model, not a trial.
Habits of mind form young. A Cambridge research review for the UK's Money Advice Service looked at planning ahead, delaying decisions and self-regulation. It found these are largely set by around age 7 (Whitebread & Bingham, 2013, as reported by Yahoo Finance). It covered these general skills, not saving itself.
If your child is 11 and has never saved a dollar, that is not a verdict. They are still inside the window the CFPB sees as prime time for money habits.
Exciting enough to matter
The goal has to be something your child wants, not something you think they should want. A specific item beats a category: the blue bike from the shop window, not "a bike someday." Goal research, mostly with adults and not about money, finds that specific, challenging goals beat vague "do your best" ones (Gollwitzer, 1999).
Find a picture of it. At 8–10, you can help narrow the list; teens choose on their own. If their pick is not yours, see our piece on supporting dreams that are not yours.
Realistic enough to finish
A first savings goal is mostly a lesson in finishing. A $600 console for a 9-year-old saving $5 a week takes 120 weeks, well over two years. That is not a goal, it is a rumor. A $40 set of art markers takes 8 weeks at $5, or 4 weeks at $10.
Big dreams still count. Keep the big one on the wall and put a nearer goal in front of it. Our guide on breaking a big goal into steps shows how.
How to teach kids to save money by age: price and time
Kids get better at thinking about time as they grow, and that should set the size of the goal. In one lab game, 11- and 12-year-olds explored more when the game would run long than when it would run short, as adults did. Five- and six-year-olds were much weaker at this (Zhuang, Niebaum & Munakata, 2023).
The samples were small (43 young kids, 40 older kids, 49 adults), and ages 7 to 10 were not tested. So the horizons below are our suggestions: short while future thinking develops, longer as it matures.
| Age | Who picks | Time to finish | Tracker and match |
|---|---|---|---|
| 8–10 | Your child, with your help | A few weeks (about 2–4) | Clear jar or chart with the picture; a small, capped match helps |
| 11–13 | Your child, with your input | About 1–3 months | Chart or app, maybe a first savings account; match optional |
| 14–17 | Your teen, who manages it | Several months | Their own system; fade the match as they earn |
The one-line formula
Price ÷ weekly saving = weeks to finish. Too many weeks for the age? Pick a cheaper goal, save more each week or add a small match. For teens, a paid job is often the fourth lever. The question shifts too, from "Can I afford it?" to "What am I giving up for it?"
Split the price into equal steps and make progress visible
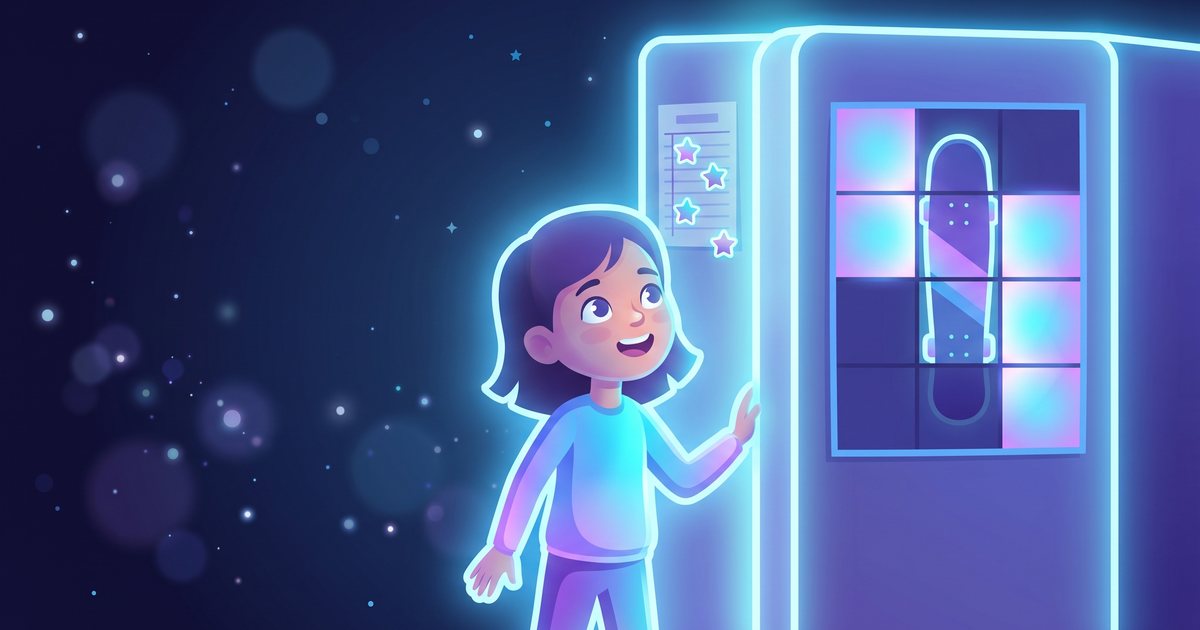
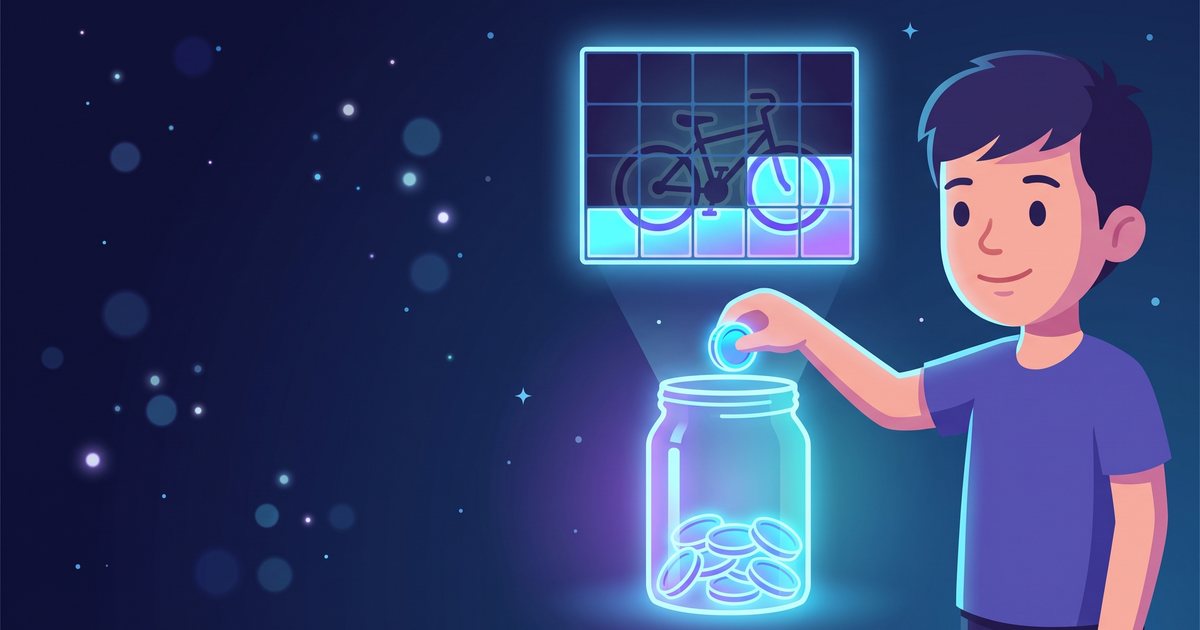
Divide the price into equal steps, each close to one typical deposit, so something changes every time money goes in. Put the steps where your child will see them: a grid over the picture, a thermometer on the fridge, squares on a jar label. Update it the moment money goes in.
What the research says
Watching progress helps effort (in adults). In a study of adults by Cheema and Bagchi, people doing a 130-second grip task kept up their effort better while watching a progress bar fill. A group shown an abstract stopwatch for the same task slipped more (Cheema & Bagchi, 2011). The task lasted about two minutes.
The caveat. The same study found that the lift from a visible progress bar weakened once the goal was broken into many smaller subgoals.
Our read
We read the two findings together. The filling picture is the motivator, and the finish line should stay single: the whole picture. Equal squares work like tick marks on a ruler, not like dozens of separate goals. The trap is turning every square into its own target and celebration until the big goal fades.
If your child likes milestones, mark three to six, not twenty. This is our interpretation of adult research on a two-minute task, not a tested rule for kids.
A worked example: the $320 bike
Say your 14-year-old wants a $320 bike. With $5 steps, the price becomes 64 squares over a picture of the bike. Here is how the weekly amount changes the wait.
| Weekly saving | Squares a week | Weeks to finish | Roughly |
|---|---|---|---|
| $10 | 2 | 32 | 7 months |
| $15 | 3 | 22 (the last week fills 1) | 5 months |
| $15 plus your $5 match | 4 | 16 | Just under 4 months |
| $40 from a part-time job | 8 | 8 | 2 months |
Mark each quarter of the picture as a milestone: 16 squares, or $80. At 4 squares a week, your teen passes one every 4 weeks. In the match row, your share over 16 weeks is $80 and your teen's is $240.
A picture whose squares fill in with each saving is the core idea behind DreamBig, our app coming soon to iPhone and Android. A printed photo, a ruler and a marker do the same job today.
Where the money comes from: allowance, earning and matching
Families fund savings goals differently, and the research pulls in two directions.
What the research says
Allowance and confidence. A 2015 T. Rowe Price survey covered 1,000 parents and 881 kids aged 8 to 14. Kids with an allowance were more likely to understand the value of a dollar (90% vs. 81%) and to feel smart about money (40% vs. 25%) (T. Rowe Price, 2015). It is an industry survey and shows correlation only.
No-strings allowance and literacy. An analysis of the 2000 Jump$tart survey of U.S. high school seniors found a less flattering pattern. Financial literacy scores were highest with no allowance (52.5%), then chore-linked allowance (52.1%), and lowest with unconditional allowance (49.1%). Nearly a third of the unconditional group had never held a paid job, versus about 15% of the chore-linked group (Mandell). Also correlational.
Matching. In a 2017 scan of 54 U.S. children's savings account programs, reported by the CFPB, 52% offered a match. The usual deal was $1 for each $1 saved, up to a fixed cap. St. Louis's College Kids program, for example, matches up to $100 a school year (CFPB, 2019). Adult research cited in that brief found that having a match at all raised saving more than its size did (Schreiner, 2001).
Our read
The two allowance surveys measured different things at different ages, so we would not crown a winner. A middle path seems sensible: some regular money, part of it tied to effort or extra jobs, and ongoing money talk. For matching, small and capped is likely enough: $1 for $1, up to $5 a week. Fade it as your child starts earning.
A short weekly family meeting is a natural home for that money talk and a look at the chart.
When your child wants to spend it all right now
Three weeks into the bike, a friend gets a new game, and the jar suddenly looks like a wallet. Willpower in that moment is a poor plan, for kids and adults alike.
What helps is deciding the rule in advance, in "if X, then Y" form. Psychologists call this an implementation intention. A plan made ahead makes the response close to automatic, instead of a fresh battle of wills (Gollwitzer, 1999). The research is general, not about kids and money. For a save jar, try: "If I want to spend my save money, I wait 24 hours and tell a parent."
Then show the cost in squares. A $60 game is 12 squares, or three weeks at $20 a week. In our view, after the 24 hours the choice is your child's. For what waiting does and does not predict, see what the marshmallow test really says.
Try this at home · 14 days
A small first goal as a test run. Your child can say no at any point, and the only comparison is with their own first try.
- Day 1: Ask whether they want to try a two-week saving experiment. If not, drop it cheerfully.
- Day 1: They pick one item that costs about two weeks of their usual money, then print or draw its picture.
- Day 1: Split the price into equal squares of about one deposit each, and draw the grid over the picture.
- Day 1: Write the 24-hour rule together and tape it beside the picture.
- Days 2–13: Each time money goes in, your child colors a square right away. No reminders, no speeches.
- Day 14: Count the filled squares together and name what got in the way.
- Decide together: finish, adjust the price or the step, or retire the experiment.
What does not work, and why
- A goal too big or abstract. "Save for college" at 8 asks a child to care about a finish line a decade away. Keep long-term accounts as your project.
- No visible tracker. An opaque piggy bank hides the progress signal that helped adults in the visualization study.
- Twenty tiny celebrations. Treating every square as its own win splits one goal into many, the version where the visual lift weakened.
- A goal you picked. Our opinion, not a finding: without your child's buy-in, it becomes your savings plan with a reluctant employee.
- No-strings money, no money talk. Unconditional allowance went with the lowest teen literacy scores. Correlational, but a nudge to tie some money to effort.
- No plan for the spend-it-now moment. Leaving it to willpower means relitigating the goal whenever something shiny appears.
Tempted to add stickers and prizes? Our piece on visible progress versus rewards covers the difference.
Key takeaways
- Start with one specific goal your child picked: exciting enough to matter, cheap enough to finish.
- Size it by age: a few weeks at 8–10, one to three months at 11–13, several months for teens.
- Split the price into equal steps of about one deposit each, and keep one finish line: the whole picture.
- A small, capped match can make a first goal feel reachable. Fade it as your child earns.
- Agree on a "wait 24 hours and tell a parent" rule before temptation shows up.
Frequently asked questions
What is a good first savings goal for a kid?
A specific thing your child chose, with a picture, priced to finish in a few weeks at 8–10 or a few months for a teen. The heart of how to teach kids to save money is finishing, so keep the first goal small.
What should a savings goal chart for kids look like?
The goal's picture, the price split into equal squares, a square colored each time money goes in and only a few milestones. DreamBig, our app coming soon, is built on this idea, but paper works fine.
Should allowance be tied to chores?
The evidence is mixed. One survey linked allowance to more money confidence; another linked unconditional allowance to the lowest teen literacy scores. A middle path: tie part of it to effort and keep talking about money.
What if my child wants to spend their savings right now?
Agree on the rule in advance: wait 24 hours and tell a parent. Then show the cost in squares and let your child make the call.
Should my child save for college instead?
Saving for your child's future is worth doing, but it is your project. To build the skill, kids need goals they can see and finish, and planning over long horizons matures around the preteen years.
This article is general information, not financial advice. If you are choosing a savings account for your child or money is a source of stress at home, talk to a licensed financial professional.
Sources
- Consumer Financial Protection Bureau (2016). Building blocks to help youth achieve financial capability: Report brief. CFPB.
- Consumer Financial Protection Bureau (n.d.). School-age children to preteens. Money as You Grow, CFPB.
- Johnson, G. (2013). Kids develop money habits by age seven: study. Yahoo Finance Canada. Reports on Whitebread, D. & Bingham, S. (2013), Habit formation and learning in young children, Money Advice Service.
- Zhuang, W., Niebaum, J. & Munakata, Y. (2023). Changes in adaptation to time horizons across development. Developmental Psychology, 59(8), 1532–1542.
- ScienceDaily (2011). Easy to visualize goal is powerful motivator to finish a race or a task. Summarizes Cheema, A. & Bagchi, R. (2011), The effect of goal visualization on goal pursuit: Implications for consumers and managers, Journal of Marketing, 75(2), 109–123.
- Gollwitzer, P. M. (1999). Implementation intentions: Strong effects of simple plans. American Psychologist, 54(7), 493–503.
- Consumer Financial Protection Bureau (2019). Child savings accounts: Using incentives to encourage participation. CFPB report.
- Mandell, L. (n.d.). Child allowances: Beneficial or harmful. lewismandell.com (analysis of the 2000 Jump$tart survey).
- T. Rowe Price (2015). T. Rowe Price: Kids who get an allowance are more money savvy than those who do not. Press release on the 2015 Parents, Kids & Money Survey. CSRwire.
Ilya Makarov is the founder of DreamBig, a visual savings-goal app for kids and teens. DreamBig Parenting articles separate what research shows from our interpretation and from practical experiments, and link every source. This article is general information, not medical, psychological or financial advice for a specific child.